Commercial Insurance
Protection for third-party death, injury and property damage
If a visitor, customer or member of the public is hurt — or their property damaged — because of your business, public liability cover is there to meet the financial risk.
What is public liability insurance?
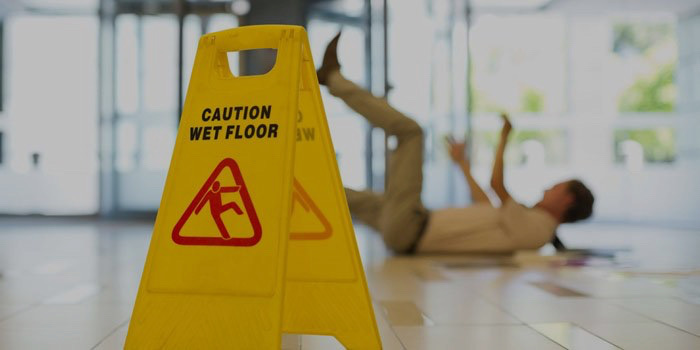
Public liability insurance provides financial protection when a third party — a member of the public or another business you work with — suffers death, bodily injury or property damage. For example: a visitor slipping on a wet floor, a visitor tripping over loose carpet in reception, or a plumber damaging a pipe that causes property damage and business interruption.
How a public liability policy protects you
A liability policy usually has two limits — one for public liability and one for products liability — and they're typically the same, for example $20 million each. Products liability covers injury or damage caused by a product you supply; public liability covers injury or damage caused to a member of the public.
Get a quote today
Personal injury cover includes
- Death, bodily injury, sickness, disease, disability, shock, fright, mental anguish and mental injury
- False arrest, wrongful detention or imprisonment, and malicious prosecution
- Wrongful eviction
- Assault or battery (unless excluded)
- Libel, slander, defamation of character or invasion of privacy, occurring during the period of insurance
Property damage cover includes
- Physical loss of, or physical destruction of, tangible property
- Loss of use of tangible property that cannot be used because of physical damage to other property during the period of insurance
Exclusions vary by insurer — your policy schedule will specify them.
From our clients
“Our dealings with KeyInsure have always been very friendly and helpful, also very quick response and professional advice. Pretty sure they save us money on our insurances also. Thank you.”
 Keylend
Who needs this cover
Public liability is the cover most businesses take out first. If members of the public, customers or other businesses come into contact with your work, your premises or your products, it is worth considering.
- Trades and contractors working on other people’s property
- Shops, cafes and any business with customers on site
- Businesses that attend markets, events or client premises
- Manufacturers, wholesalers and importers that supply products
- Property owners and landlords of commercial premises
- Sole traders and consultants who visit clients
What affects your premium
Public liability premiums vary widely. These are the factors insurers typically look at when pricing a policy.
Your industry and activities
Some trades and professions carry more risk than others, and insurers price accordingly.
Turnover and size
Annual revenue, number of staff and number of sites all feed into the premium.
Limit of cover
A higher limit costs more. Contracts and site requirements often set the minimum you need.
Excess
Choosing a higher excess usually lowers the premium; a lower excess raises it.
Claims history
Past claims — yours and, in some cases, the industry’s — affect what insurers offer.
Risk management
Documented safety procedures, training and contracts can help at renewal time.
Common questions
Is public liability insurance compulsory?
It is not required by law for most businesses, but many landlords, councils, principals and event organisers require it as a condition of a contract or a site licence. Some licensed trades are required to hold it.
What limit of cover do I need?
Limits vary, and contracts, councils and site owners often specify a minimum. The right level depends on your contracts, the sites you work on and the size of the losses your business could face. We can help you compare the options.
Does public liability cover my own staff?
Typically no. Injury to your own employees is covered by workers compensation, which is a separate scheme required in each state and territory. Public liability responds to claims from third parties.
What is the difference between public and products liability?
Public liability covers injury or damage caused by your business activities or premises. Products liability covers injury or damage caused by products you sell, supply or manufacture. They are usually written together in one policy.
Does it cover professional advice?
Generally not. Claims arising from advice, design or professional services fall under professional indemnity insurance, which is a separate policy.
Related cover
Ready when you are
General advice only. Consider the relevant PDS & TMD before acquiring any product.